Credit Card Casinos: Two Rulebooks, One Card
A credit stake is the issuer's money at the table's price. Two rulebooks govern the card, and only one of them has banned it.
The table score
Four operators, weighed the way a croupier weighs a table: the entry price, the terms weight, the rails on offer, and how fast the cage pays. The scores are ours; the offers are quoted in the operator's own words.
Every card carries its table score out of 10 and four axis bars - licence, terms, payments and withdrawal. Offers move often - the operator's own page is always the current truth.
Welcome bonus €/£5,000 + 500 FS
Weigh the offer
Welcome pack €5,000 + 500 FS + €650 free bet
Weigh the offer
Casino welcome bonus 805% up to €6,400 + 280 FS
Weigh the offer
Welcome package 300% up to €/£1,000 + 150 FS
Weigh the offerCards appear in table-score order, the lower minimum deposit breaking ties. The bars visualise published figures, not a promise; nothing here is a recommendation to gamble, and the operator's own terms decide every claim.
What a credit card casino is, weighed honestly
The phrase describes a room whose cashier accepts a credit card as a funding rail, and in Britain the honest description starts from a date: since April 2020, the Gambling Commission has prohibited credit cards at British-licensed gambling, online and off. The rule followed a review that weighed staking borrowed money against the harm it was linked to, and it removed the rail from every room holding a British licence. What the search term therefore describes, in practice, is a room licensed elsewhere that still takes the card.
That makes the page a comparison of rulebooks rather than a shopfront. On one side stands the British rulebook, which treats staking money not yet held as a harm to be prevented and has closed the rail at licensed rooms. On the other stand offshore rulebooks, which set their own cashier rules, several of which permit the card. The card itself is indifferent; it works wherever it is pointed. The rulebook is what decides, and the rulebook is what this page weighs.
The felt, as ever, takes no notice. A single-zero wheel carries 37 pockets and a house fraction of 2.70 per cent, whether the float arrived on credit, debit or dollar coin; a 6 to 5 natural trims the price on any funding method. What the funding method changes is the player's own position: money staked that was never held, at interest that runs whether the hand wins or loses. That position is the subject of the middle of this page.
Two rulebooks, one card
The British rulebook's position is a prohibition, enforced at the cashier: a British-licensed room may not accept the card for gambling, and its payment systems are built to decline the rail. The offshore rulebook's position is permission, in many cases: an operator licensed in Curaçao or a similar jurisdiction may accept the card, and some do. Both positions are lawful where they apply. The difference the player feels is not legality but protection - who wrote the rule, who checks it, and who answers when it is broken.
Acceptance is therefore a flag, said plainly and without dressing: a room that welcomes a credit card from a British player is telling the player which rulebook it runs under. Hedged as industry-wide rather than room-by-room, the same flag usually travels with others - self-exclusion tools of the British kind, affordability checks of the kind British rooms run from February 2024, and independent dispute schemes all attach to the British licence rather than the offshore one. The card is welcomed precisely where those protections stop, and that is the geometry of the offer.
The debit side of the same networks sits inside the British rulebook, and the debit rails the same networks run weighs that half properly: spend-you-have stakes, at rooms whose cashiers were built around the ban. A player who wants the card-network convenience without the borrowed stake has a lawful British route on the same plastic, and the difference is one letter - debit rather than credit - with a whole rulebook attached to it.
Credit card casino at a glance
- Entry price£20 typical
- Wagering50x on bonus
- Payout window1–3 working days
- Payments4 rails incl. e-wallet
The price of a borrowed stake
A credit stake carries two prices, and only one is printed on the table. The table's price is the house edge, familiar from every page on this site. The card's price is interest: gambling transactions on credit cards are commonly treated by issuers as cash-type transactions, which in many cases means interest runs from the day of the deposit rather than from a billing date, and commonly at rates above those charged on purchases. Neither figure appears at the cashier; both appear on the statement.
Worked in the clerk's units: a £200 stake funded on credit and cleared a month later has paid interest on the full amount for the month, at the card's cash rate, before a single result is counted. If the stake loses, the loss is £200 plus the interest; if it wins, the win is smaller than it looks by the same interest. The gap between the face of the stake and its true cost is the same gap this site weighs between paid odds and true odds - only here the party taking the extra fraction is the issuer.
The direction deserves stating without numbers, because rates are issuer-specific and move with the market. Interest from day one on a losing position makes every loss larger than it was, and makes chasing a loss more expensive by the hour. A rail that adds cost to losing faster than it adds cost to winning is, by construction, a rail that deepens the exact behaviour staking borrowed money encourages. That is the arithmetic behind the British ban, and it is arithmetic rather than opinion.
What the card does to the tally
The tally on this site is what actually leaves, and a credit card breaks the tally's basic unit. A debit stake comes out of money held; the balance falls, and the session's cost is visible the same day. A credit stake comes out of money owed; the funds held do not fall, the statement lands weeks later, and the session's true cost arrives after the memory of the session has faded. Distance between act and cost is precisely what a tally exists to prevent.
The break compounds at the tables. Table games move money quickly - a live shoe at 50 to 70 hands an hour turns a float over dozens of times in an evening - and a rail with no immediate ceiling lets a bad hour become a large figure before any statement says so. Prepaid vouchers, phone-billed rails and pre-funded wallets all share one design virtue the credit card lacks: the money on the table was already the player's, and when it is gone, the rail is done.
Statements soften the blow by design. Minimum payments reframe a lost stake as a manageable monthly line, and the interest section of this page runs quietly underneath for as long as the balance survives. A player reading their own tally honestly should read the full statement rather than the minimum, and add the interest line to the gambling line, because the issuer's fraction is part of the stake's cost whether or not the room's cashier mentions it.
A worked pair makes the break visible. Two players stake £100 each at the same table and lose the same hour. The debit player's account is £100 lighter by teatime, and the week's budget absorbs it. The credit player's account is untouched on the day, the statement arrives in three weeks showing £100 plus interest, and the minimum payment due is a fraction of it - a figure small enough to repeat. Same table, same hour, same loss, and two completely different papers at the end of it.
| Brand | Welcome offer | Wagering | Min dep. | Withdrawal | Payments | Licence | Table score | Terms |
|---|---|---|---|---|---|---|---|---|
| Pub Casino | Bet £10 get £30–£40 (typical) | 30x–40x by productbest | £10+5 | 1–3 working days+3d | Visa · PayPal · Paysafecard · Bank transfer-1 rails | UKGC | 8.2 / 10 | Check the terms first |
| Betfair | £20–£50 free bet or cashback (typical) | Commission model — no bonus wagering | £10+5 | 1–2 working days+2d | Visa · Mastercard · Skrill · Apple Pay-1 rails | UKGC | 7.9 / 10 | Check the terms first |
| Velobet | 100% up to €/£1,000 + spins (typical range) | 30x–45x by gamebest | €10 equivalent+5 | Instant–24h on cryptobest | Bitcoin · Litecoin · Visa · Bank transfer-1 rails | Offshore | 6.8 / 10 | Check the terms first |
| MrQ | Bet £10 get £30–£40 (typical) | 30x–40x by productbest | £5–£10best | Under 24h e-wallets+24d | Visa · Mastercard · Neteller · Pay by mobile-1 rails | UKGC | 6.6 / 10 | Check the terms first |
| Parimatch | Matched welcome up to €/£300 (typical) | 30x typicalbest | €20+15 | 1–3 working days+3d | Visa · Mastercard · Trustly · Bank transfer-1 rails | Offshore | 6.4 / 10 | Check the terms first |
| Dream Jackpot | 100% up to £/€100 + spins (typical) | 40x typical+10x | £10–£20+5 | Under 24h e-wallets+24d | Visa · Mastercard · PayPal · Bank transfer-1 rails | UKGC | 5.9 / 10 | Check the terms first |
| JackpotCity | 100% up to €/£100 + 50 spins (typical) | 30x typicalbest | €10–€20+5 | 2–5 working days+5d | Visa · Mastercard · Trustly · Bank transfer-1 rails | Offshore | 5.9 / 10 | Check the terms first |
| 10bet | 100% up to €200 + spins (typical range) | 40x typical+10x | €20+15 | 1–3 working days+3d | Visa · Mastercard · Skrill · Neteller-1 rails | Offshore | 5.7 / 10 | Check the terms first |
| Mystake | 100% up to €/£1,000 + spins (typical range) | 35x typical+5x | €20 equivalent+15 | Under 24h on crypto+24d | USDT · BTC · ETH · TRX · Visabest | Offshore | 4.9 / 10 | Check the terms first |
| Boneenbet | 100% up to €/£1,000 + spins (typical range) | 35x typical+5x | €10 equivalent+5 | 24–48h (crypto fastest)+48d | Bitcoin · Litecoin · Visa · Bank transfer-1 rails | Offshore | 4.5 / 10 | Check the terms first |
| NineWin | Matched deposit up to €/£500 + spins (typical) | 45x typical+15x | €10–€20+5 | 24–48h (crypto fastest)+48d | BTC · ETH · USDT · MuchBetter-1 rails | Offshore | 3.8 / 10 | Check the terms first |
| Fat Pirate | Crypto match up to 1 BTC equivalent (typical) | 45x typical+15x | €20 equivalent+15 | 24–48h (crypto fastest)+48d | Bitcoin · Litecoin · Visa · Bank transfer-1 rails | Offshore | 3.8 / 10 | Check the terms first |
The rails a player can use instead
The substitutes are many, and they divide by one test: whether the money staked was already held. Debit cards pass the test and keep the card-network convenience, at British-licensed rooms where the ban is enforced at the cashier. Prepaid vouchers pass it harder still, bounding the spend at whatever face value was bought. Pre-funded wallets pass it when the funding source is honest, and phone-billed rails pass it by carrying small caps by design.
The second network gets the same read from its own page: the other network's debit half covers the mastercard route, where the same one-letter difference separates the lawful British rail from the borrowed one. Between the two networks and the smaller rails, a British player is short of nothing except the credit itself - which is the point. The ban removed one rail; it left the transport of money to the tables entirely intact.
Speed is the usual objection to the substitutes, and it is a thin one. Debit deposits clear in seconds at most rooms; payouts run quicker at fast-withdrawal operators than card settlements ever did; and the wallet rails carry timing cards of their own. What the substitutes cannot offer is a float made of money not yet held - and a player whose plan requires that float has a problem the rail cannot solve, which is a better sentence to read than a statement to receive.
Budgeting tools finish the set. Deposit limits at the room, capped rails, vouchers bought weekly - each draws the line at a different point, and the right point is the one that holds on a bad evening rather than a good one. A rail chosen for its brakes is not a lesser choice; it is the choice that matches the game's pace, which at 50 to 70 hands an hour is quick enough to outbuild any intention set after the first hand.
If the card is already in play
The card already funded is a position to close rather than a mistake to relitigate. The practical sequence is short: stop staking on the card, read the current balance and the rate honestly, and pay the balance down as the first call on money that would otherwise be staked. Interest does not wait for the mood to pass, and the earlier the balance is cleared, the smaller the issuer's share of the story.
Two tools shorten the road. Many issuers offer gambling blocks on request, which decline gambling transactions at source - hedged, because implementations vary by issuer and some take a period to apply. The national self-exclusion register is built for British-licensed rooms, and a registration there closes the lawful door; offshore rooms sit outside the register, which is one more reason the offshore card acceptance on this page reads as a flag rather than a feature. Free, confidential support exists for the stopping itself, and the signposting on this site points to it.
The last tool is the statement, read as a tally. Add the gambling lines to the interest lines for the honest figure, date the habit from the first statement it appears on, and keep the file - because a player who can show themselves the real cost of a borrowed stake holds the same weapon this site hands every reader: figures before adjectives. The card in play is arithmetic, and arithmetic can be worked down to zero.
Checks to chalk before the card comes out
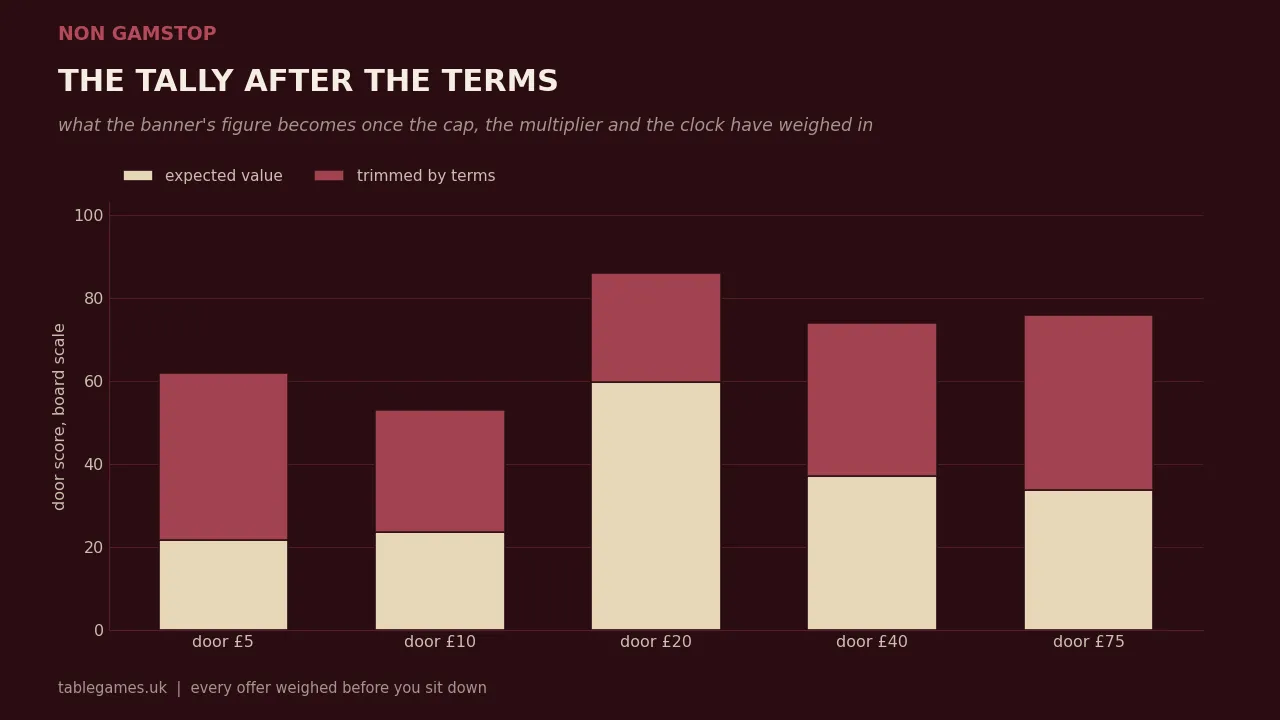
The card is the one rail this site declines to weigh as a neutral option, and the card below is why: every line on it runs one way. British rooms cannot take the stake; offshore rooms that do are naming their rulebook; the interest runs from the day; and the tally breaks at exactly the moment it is needed most. Read as a whole, the card is not a weighing between two prices but a record of one price paid twice.
The card, chalked in full:
- British-licensed rooms have declined credit-card gambling since April 2020.
- An offshore room accepting the card is naming its own rulebook.
- Interest commonly runs from the day of the deposit, not the bill.
- A lost stake on credit costs the stake plus the interest.
- Ask the issuer for a gambling block; many offer one on request.
- Fund play from money held: debit, wallet, voucher or phone rail.
The tables will take the money from wherever it comes; they always have. The rulebook, the interest and the broken tally are the player's side of the ledger, and they are the side this page exists to weigh. Leave the credit line out of the stake box and the felt's own price is the only one left to pay - which is, on the evidence of every fraction this site has ever chalked, quite enough.
Frequently asked questions
Can I use a credit card at a UK casino?
Not at a room licensed in Britain: the Gambling Commission has prohibited credit-card gambling since April 2020, and licensed rooms' cashiers are built to decline the rail. Rooms that do accept the card from British players are licensed offshore, where the British rulebook does not run. The acceptance itself is the clearest signal on the page about which rulebook a room operates under, and this site chalks it as a warning about the rulebook, not as a perk.
Why did Britain ban credit card gambling?
The Commission's review weighed the evidence and concluded that gambling with borrowed money was linked to harm, with card-funded play over-represented among problem gamblers; the prohibition followed in April 2020. The logic is arithmetic as much as anything: a stake funded on credit costs interest from the day it is placed, which deepens losses and speeds the chase. The ban removed the rail at licensed rooms while leaving debit and pre-funded alternatives untouched.
What does a credit card deposit actually cost?
The room commonly charges nothing; the card is where the cost sits. Issuers commonly treat gambling transactions as cash-type, meaning interest runs from the day of deposit at a rate often above purchases, with no interest-free period in between. A £200 stake carried a month adds pounds to the cost before any result counts, and the add-on repeats for every month the balance survives. The statement, not the cashier, is where the true figure is printed.
Do debit cards work the same way?
No, and the difference is the money rather than the network. A debit stake comes out of funds actually held, so the tally of what leaves is accurate the same day and the issuer's interest never enters the picture. The networks are identical, the convenience is identical, and the cashier speed is comparable at most rooms. One letter - debit rather than credit - is the whole distance between the lawful British rail and the borrowed one.
Can a credit card deposit be reversed?
Chargeback schemes exist for specific cases - unauthorised use, or services not provided - hedged as issuer-and-scheme dependent, because outcomes vary. What chargeback is not is an undo button for a losing stake: the bet was placed, the game was played, and a loss is not a failed delivery. Treating reversal as a plan is the most expensive reading of this page. The reliable figures remain the ones printed before the deposit: the room's terms and the card's rate.
How do I stop gambling on a credit card?
Four lines, in order. Ask the issuer for a gambling block, which many offer on request and which declines gambling transactions at source. Register on the national self-exclusion scheme, which covers British-licensed rooms. Name the situation to the free confidential services the site signposts, which exist for exactly this conversation. And read the statement as a tally - gambling lines plus interest lines - so the true cost is dated and visible. The balance only goes one way once staking stops.